Material risk
Understand the business context and the risk.

Capability
Connect risks, controls and operating evidence to management action, with a clear scope and defined professional responsibility for every review.
A reporting obligation, concern about a control, incident or dispute calls for a precise question and appropriate evidence access. Explore the relevant area below, or start a conversation about your context.
Audit and assurance
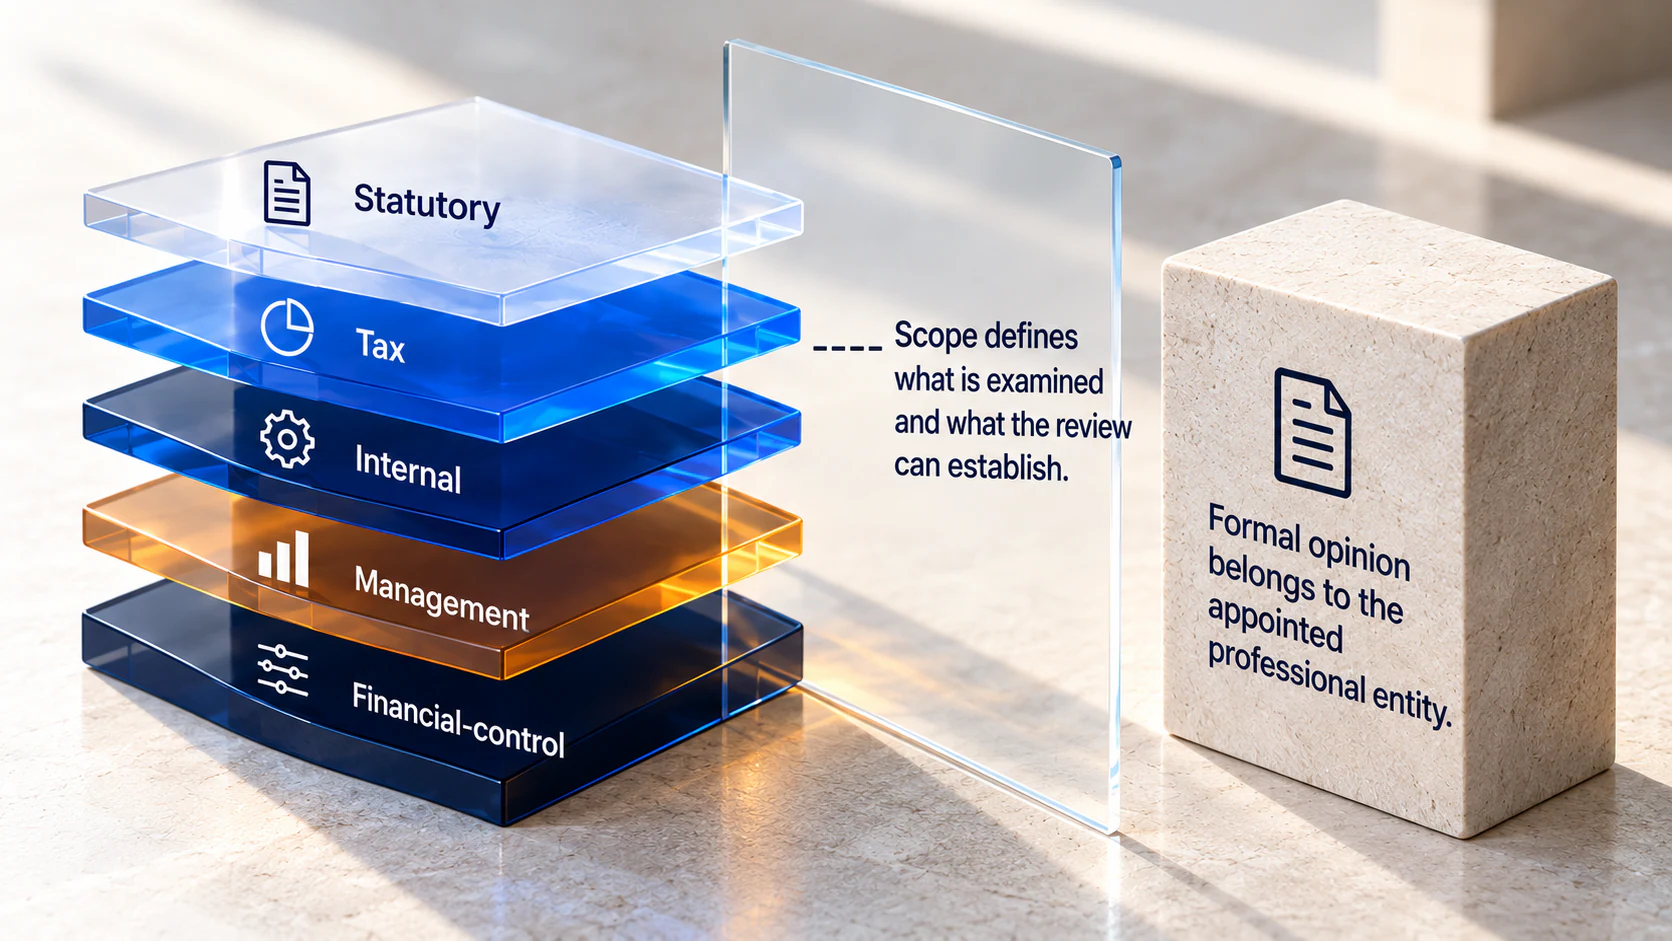
Statutory, tax, internal, management and financial-control reviews address different needs. Start with the question, the relevant records and the intended use of the review. Any formal audit or assurance engagement must identify the appointed professional entity and the applicable independence requirements.
The agreed scope determines what is examined and what the review can establish. Responsibility for a formal opinion belongs to the appointed professional entity.
Audit, risk & compliance
Risk and internal controls
Map material business risks and examine both control design and operation. A documented control describes what should happen; operating evidence helps establish what actually happens, who is responsible and where further examination is needed.
Understand the business context and the risk.
Review the documented control and what should happen.
Consider evidence of what actually happens, who is responsible and where further examination is needed.
Bring the information together to identify areas for further examination.

Management retains ownership of controls and corrective action.


Business context, control descriptions, evidence owners and previous findings help focus testing on remaining exposure. Management retains ownership of controls and corrective action.
Audit, risk & compliance
Forensic and investigation support
A suspected fraud, incident or dispute requires a defined question, controlled evidence access and clear professional responsibility. Scope the evidence work around relevant records, access permissions and confidentiality constraints. Observed evidence and its evaluation must remain distinct from the allegation that prompted the review.
The review should establish what the available evidence supports, what remains uncertain and where further examination may be needed.

From the evidence question
A defined question, controlled evidence access and clear professional responsibility.

Clarify the concern and scope the evidence work around relevant records, access permissions and confidentiality constraints.

Review relevant records with controlled access and appropriate permissions.

Keep observed evidence and its evaluation distinct from the allegation that prompted the review.

Establish what the available evidence supports and what remains uncertain.

Identify where further examination may be needed.
Corporate and operating compliance
Corporate, labour, industrial, establishment and contractor obligations need to be understood in their operating context. Review how those obligations appear in records, accountable responsibilities and management action across the relevant entities and sites.
An obligation list alone does not establish compliance. Expected records, observed gaps and exceptions help identify what requires review and who is responsible for responding.
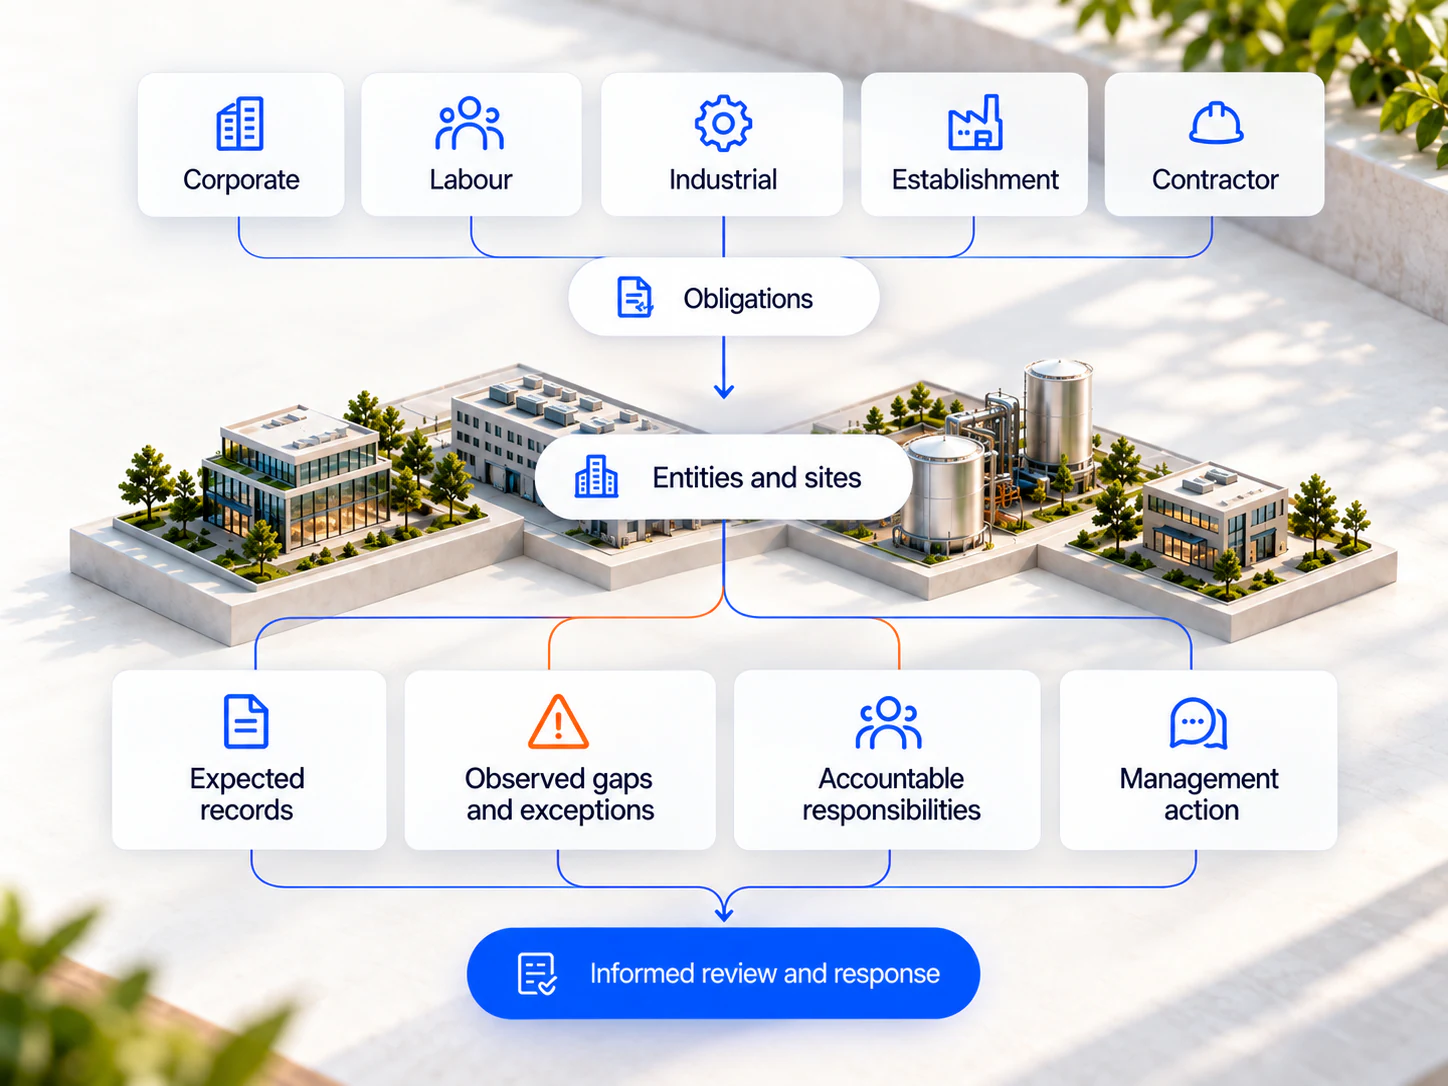
A review becomes useful when its observations, interpretation and response are clear. These responsibilities connect, but they are not interchangeable.
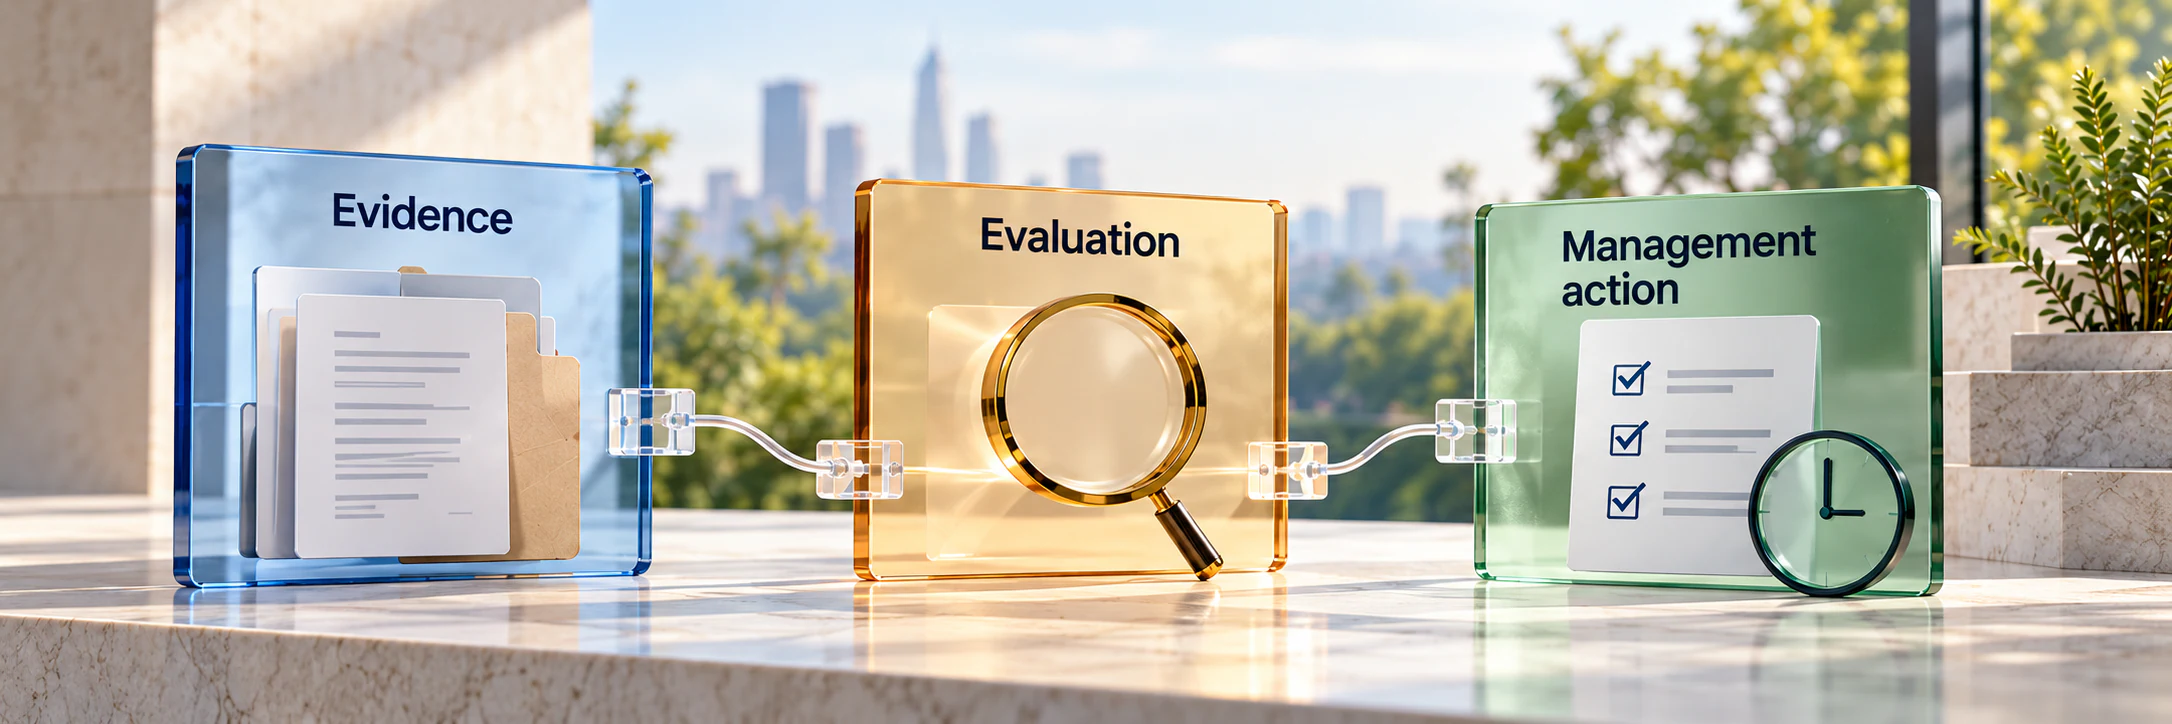
Process and financial records, control descriptions and operating evidence show what was observed and where gaps remain. Access and confidentiality constraints define what can be examined.
Consider the evidence against the review question, material risks and agreed scope. Explain findings, limitations and matters requiring further examination.
Connect the response to accountable owners, timing and follow-up evidence. Recurring review can make unresolved exceptions and corrective action visible to management and oversight forums.
Need to examine a financial decision?
Explore valuation, transactions, tax questions, reporting and budgetary control when the need concerns value or commercial consequences.
Explore Finance
Need ongoing workforce or site support?
Explore payroll, contractor, field and shared-service scope when the need concerns recurring records, handoffs and operating responsibilities.
Explore Workforce
Share a brief description of the review, control concern or operating issue, along with any important timing. You do not need to choose a service before starting a conversation.
Start a conversation