01
Current process / Proposed change
What changes, and what operating purpose does it serve?

Banking and insurance
Banking and insurance service processes connect operating decisions with evidence and control responsibilities. Change, review and transactions need a clear view of what supports the decision and who is responsible for acting.
Service processes & governance
A proposed change can affect the information collected, the handoff between functions and the responsibility for a control. Understand those effects alongside the operating purpose.
ContextBanking and insurance
Process redesign, procedures and governance may clarify operating routines within an agreed scope.

What changes, and what operating purpose does it serve?
Which information is collected, and where does responsibility pass?
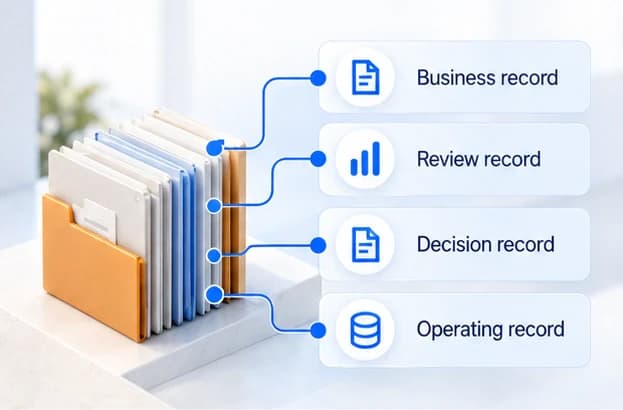
Who owns the control, and which obligations need consideration?
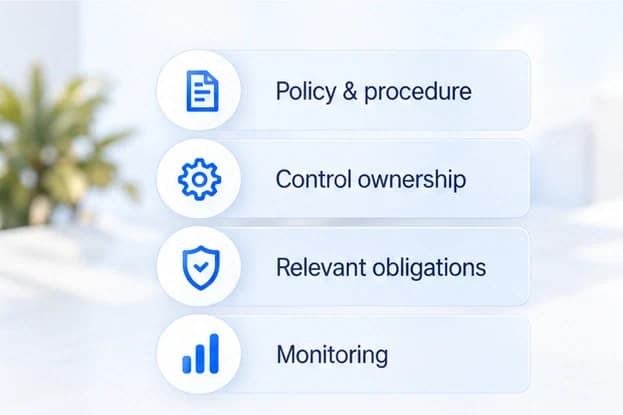
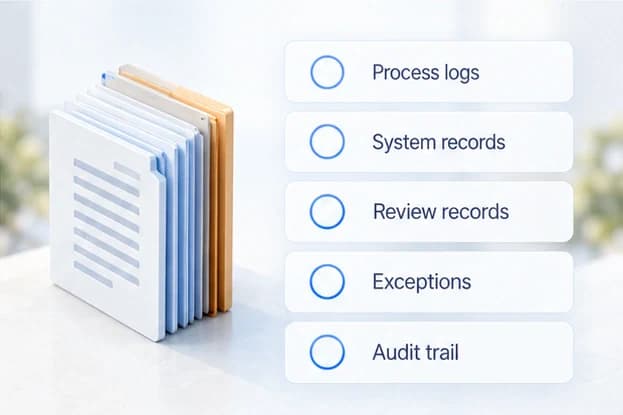
What would show how the revised process operates?
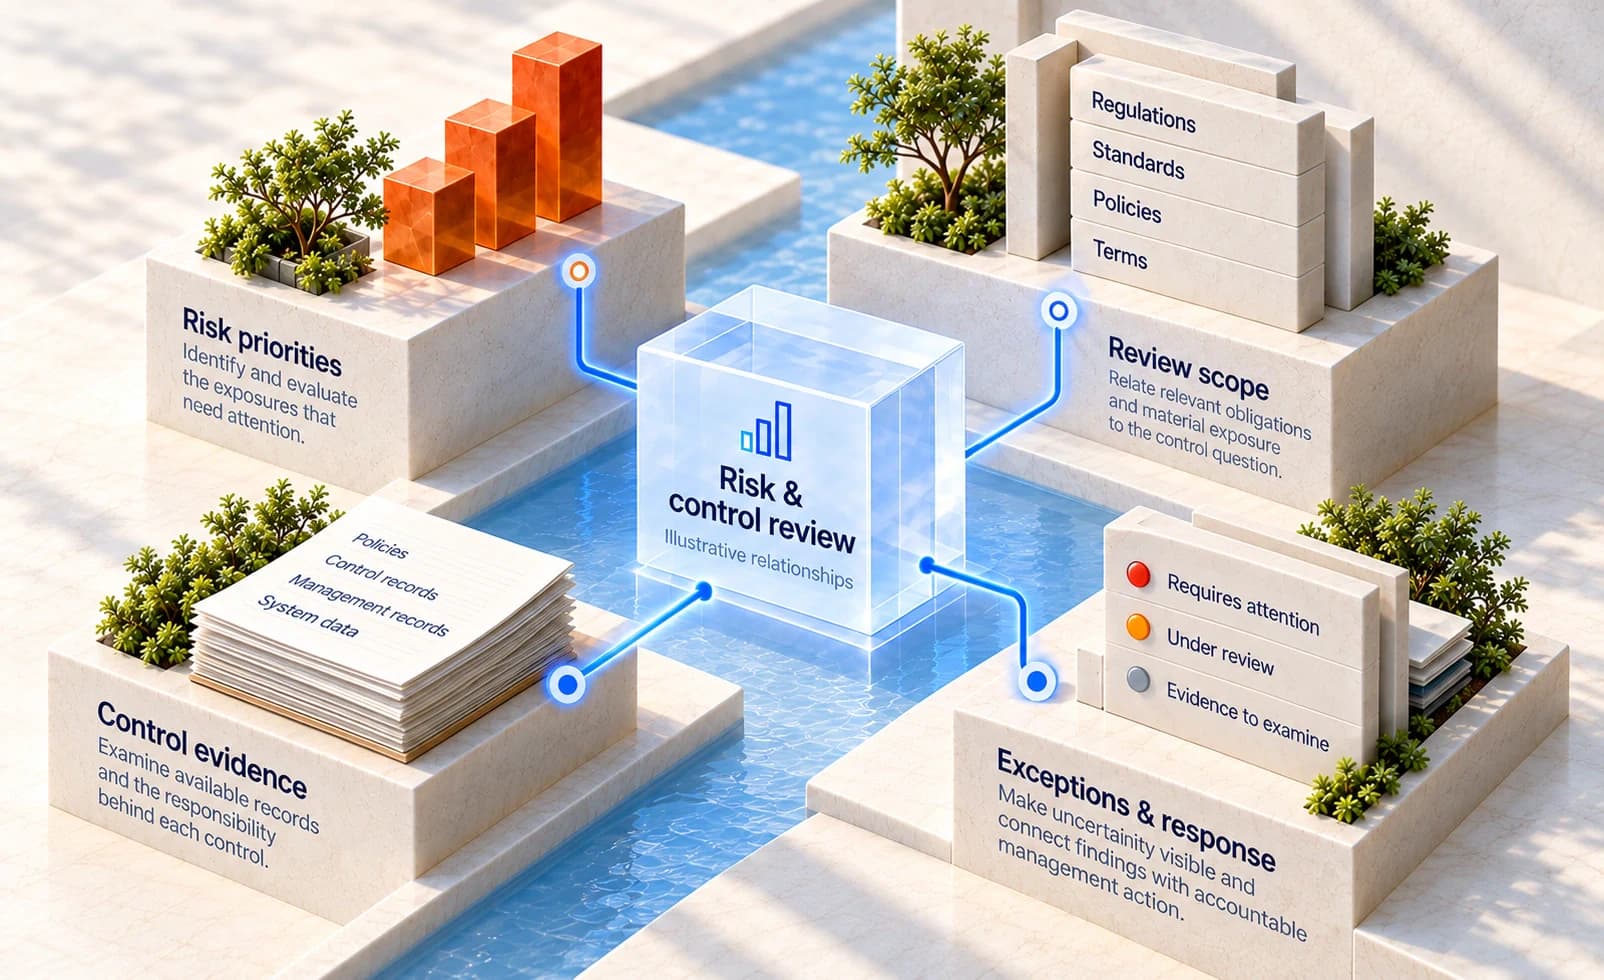
Risk and control review
Risk priorities and relevant obligations shape what needs examination. Control records and exceptions help the responsible reviewer understand what is supported and what remains uncertain.
Identify and evaluate the exposures that need attention.
Relate relevant obligations and material exposure to the control question.
Examine available records and the responsibility behind each control.
Make uncertainty visible and connect findings with accountable management action.
Formal audit or assurance depends on the appointed professional entity, competence, independence and agreed scope.
Explore Audit, risk & complianceTransaction decisions
A transaction decision brings together commercial terms, financial assumptions and the operating implications of the commitment. The evidence should answer the decision being considered.
Frame the transaction or restructuring decision.
Examine commercial commitments and the financial assumptions they depend on.

Connect financial records with operating responsibilities and implications.
Identify missing information and relevant diligence, valuation, structural or tax questions.
Formal professional work requires confirmation of the responsible provider and agreed scope.
Diligence, valuation, restructuring and tax detail continues in Finance. These are possible applications, not investment advice or product recommendations.
Management information
Useful reporting connects the record, the exception, the responsible owner and the action that follows.

Connect management records with the question under review.
Make process or control findings visible with their source evidence.
Identify who needs to act and who receives the information.
Connect the response with follow-through.
Bring the relevant evidence and open actions into view.
Management information systems, dashboards, workflow and automation may support these connections when the decision and control purpose are understood.
A possible control or process roadmap records owners and monitoring. Review findings and transaction decision support retain their source evidence and professional responsibility.
Relevant support
Explore the expertise relevant to the decision in front of you.
Transaction assumptions, diligence, valuation, restructuring and financial decisions.
Explore Finance
Service-process change, operating procedures and governance.
Explore Strategy
Let’s talk
Share the banking or insurance context, the decision that needs attention and its timing.
Relevant obligations, available business records and the responsible management team can help frame the conversation. Begin with what you know.
Start a conversation